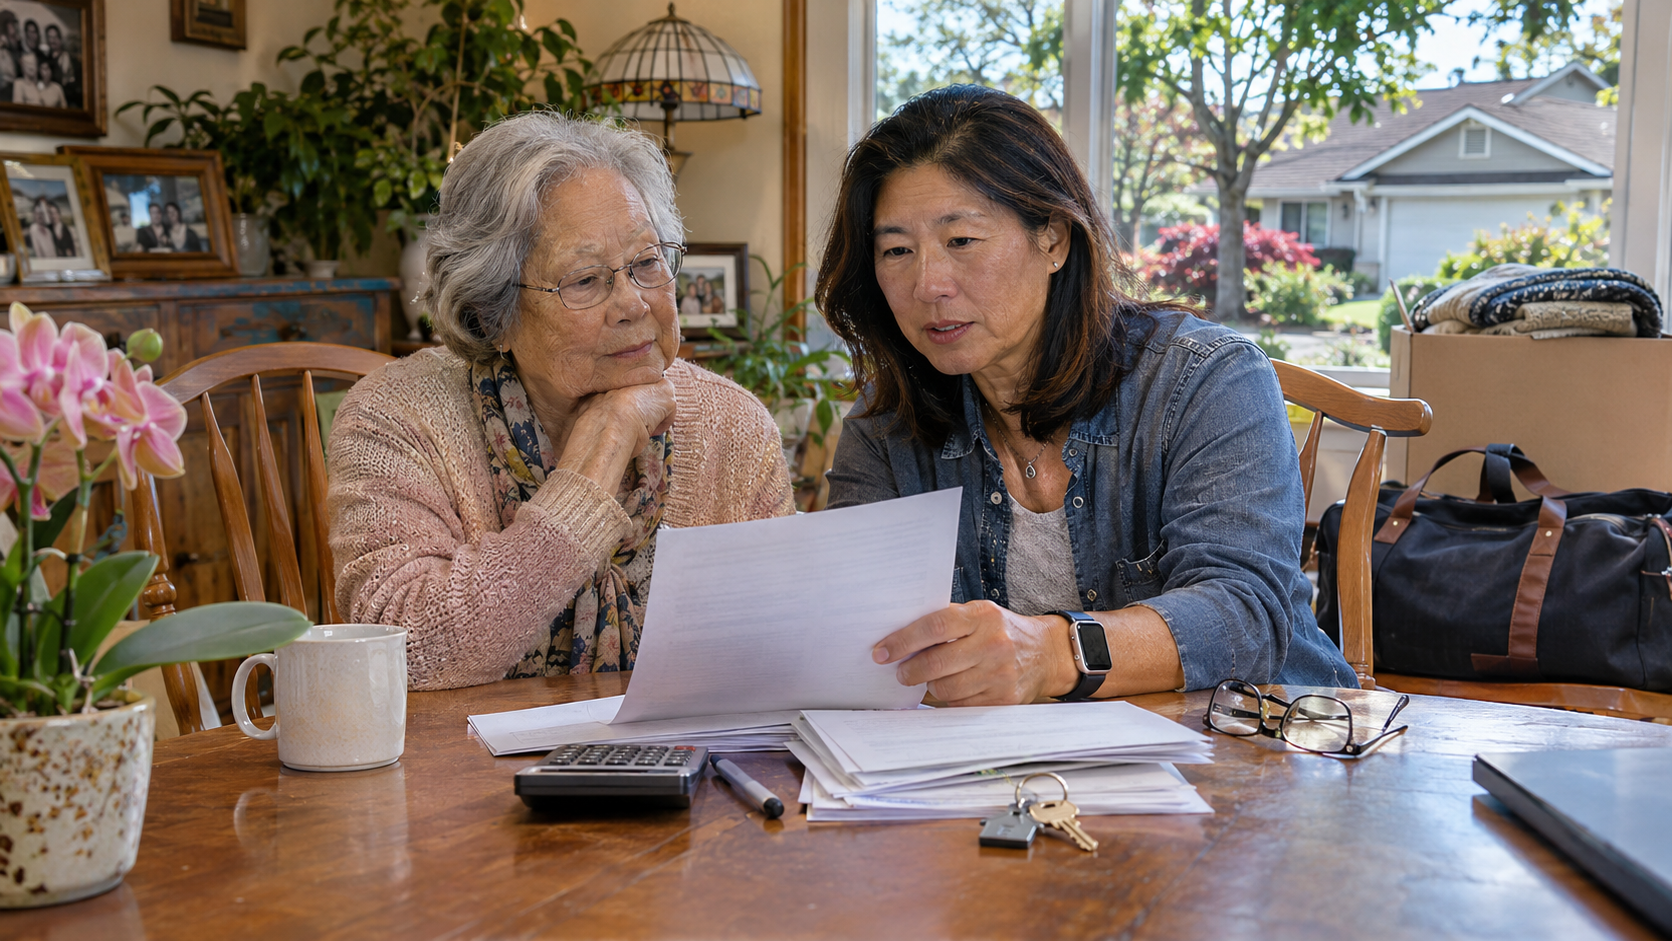
If your mom or dad has a reverse mortgage and assisted living is suddenly on the table, the short answer is that the loan doesn’t come due the day they move, but a clock usually starts that day. On the federally insured kind of reverse mortgage, called a HECM, the home has to stay the principal residence of at least one borrower, and a borrower can generally be away in a healthcare facility for up to 12 consecutive months before the lender can call the loan due. Let’s go through how the rule works, who can stay in the house, and how to protect the equity your parents spent a lifetime building.
Key Takeaways
Summary: A reverse mortgage usually survives the first months of assisted living, but when the last borrower won’t be coming home, the family should get the payoff figure and a current home value early, tell the servicer what’s going on, and plan a sale or payoff before the loan is called due, because the balance keeps growing every month you wait.
How the 12-Month Rule Works When a Parent Moves to Assisted Living
Federal regulations spell out when a HECM can be called due. Under 24 CFR 206.27, the balance can become due, with HUD’s approval, if the home stops being a borrower’s principal residence and no other borrower lives there, or if a borrower fails to occupy it for longer than 12 consecutive months because of physical or mental illness and no other borrower lives there. The Consumer Financial Protection Bureau’s guidance on moving out for medical reasons specifically names assisted living, along with hospitals, nursing homes, and rehab centers.
Here’s where families get tripped up: they hear “12 months” and assume it’s a free year. It’s really the longest your parent can be away for health reasons while the home still counts as their residence. The rule protects someone who’s recovering from a hip replacement or trying out a community and might come home, but it doesn’t protect a home nobody plans to return to.
The reason for the move matters too. The CFPB’s reverse mortgage rights and responsibilities guide says that if there’s no co-borrower in the home, being away for more than six months for non-medical reasons means the home is no longer the principal residence. So if Dad moves into your spare bedroom in Sacramento instead of a licensed community, you may not get 12 months at all. The same guide says to let the servicer know about any absence of two months or more.
And loan servicers do find out. Every year your parent gets an occupancy certification to sign and return, and servicers can also rely on returned mail, property inspections, and public records. Please don’t let anyone sign that form saying Mom still lives there if she doesn’t. That’s a false statement on a federally insured loan, and if your parent can’t sign, whoever holds power of attorney should call the servicer and ask how they want it handled.
A quick note for Silicon Valley families: the 2026 HECM limit is $1,249,125, and plenty of homes around here are worth a lot more, so some owners took out a private “jumbo” reverse mortgage instead. Those aren’t FHA-insured, and the HUD rules I’m describing here don’t automatically apply. Pull the actual loan documents and read the occupancy and repayment sections, or have an attorney do it, before you assume anything.
Free Downsizing Strategy Call
Before you start sorting decades of belongings or call a moving company... let's figure out where you're headed and how to get there.
Most downsizing regrets come from doing things in the wrong order. In 30 minutes, we’ll talk through what your home may be worth, whether to buy or sell first, how Prop 19 could affect your property taxes, what the house actually needs before listing, and a realistic timeline for your move—so the process feels manageable, not overwhelming.
Book My Downsizing Strategy Call →Who Can Stay in the House After a Parent Moves Out?
The answer depends on whose name is on the loan, so pull the paperwork before you do anything else. Here’s how each situation usually plays out.
A co-borrower. If both of your parents are borrowers and one moves to assisted living, the loan just keeps going. The parent at home can stay and, according to the CFPB, keep receiving loan disbursements, as long as they keep meeting the loan’s requirements. This is also a good time to talk about what happens when the second parent needs care, while nobody’s in crisis.
A non-borrowing spouse. Plenty of couples took the loan in one name, often because one spouse was under 62. For HECMs with case numbers assigned on or after August 4, 2014, HUD’s Mortgagee Letter 2021-11 allows the due date to be deferred when the borrower has been in a healthcare facility for more than 12 consecutive months, if the home remains the principal residence of an Eligible Non-Borrowing Spouse who meets all of HUD’s requirements. That generally means they were married when the loan closed, they’ve stayed married, and they keep living there and keep up the taxes, insurance, and home. Older loans work differently, so ask the servicer which track applies. A spouse who stays under a deferral generally can’t draw any more money from the loan, which can be a big surprise if those draws have been paying the bills. The CFPB has a helpful explanation of this one.
Anyone else is not allowed to stay in the house. An adult child who’s living in the house, even one who moved home to take care of Mom, has no right to stay under the reverse mortgage. That’s a hard conversation, especially when a son or daughter has given up a job or an apartment to help, so I’d bring it up early and give everyone time to make a plan.
What Happens When the Reverse Mortgage Comes Due
Once the last borrower’s absence or move triggers the loan, the servicer asks HUD for approval and sends a due and payable letter. Under the industry’s own explanation of the process, you generally have 30 days to respond and say what you plan to do, the servicer orders an appraisal, and you may get up to six months to pay off the loan. Two more 90-day extensions are possible with HUD’s approval if the house is actively being marketed or financing is in the works. If everything gets used, that clock can stretch to about a year. The regulations also require the lender to start foreclosure within six months of the due date unless HUD gives it more time, so don’t let those letters pile up on the counter.
Three things about the money tend to calm families down. First, the lender doesn’t get the home just because the loan came due. If it sells for more than the payoff, your parent keeps the difference. Second, a HECM is non-recourse. If the home is worth less than the balance, FHA insurance generally covers the gap, and nobody writes a check for it. Third, adult children aren’t personally on the hook unless they signed as borrowers, which they almost never did. If the loan’s underwater, the CFPB says a sale may be allowed at the lesser of the amount owed or 95 percent of the appraised value.
The piece that does cost money is time. A reverse mortgage balance grows every month, because interest and mortgage insurance get added to what’s owed. At a blended rate of 7.5 percent, for example, a $600,000 balance is adding roughly $3,750 a month, and that’s before you count the property taxes, insurance, utilities, and gardener on a house nobody’s living in. In Silicon Valley there’s often a lot of equity left, so what you’re protecting against is a slow leak.
Free 3-minute decision check
Stay, downsize, or move away? Find out which one costs you the least.
For longtime Bay Area owners, the wrong call can cost six figures in taxes, remodeling, or years of higher living costs. Answer a dozen quick questions and see all three paths side by side, with a rough dollar figure for what each one would cost you or free up.
See My Best Path →Rather talk now? Call or text 408.413.3087
Your Family’s Options, From Most to Least Common
Sell the home on the open market. This is what most families end up doing, and for a good reason, since the sale pays off the loan and whatever’s left can pay for care. I’ve written a whole piece on selling a home to pay for assisted living that goes deeper on this. Your parent doesn’t need to wait for a due and payable letter to sell, either. You’ll usually do better selling on your own schedule than with a foreclosure timeline hanging over the deal.
Pay off the loan and keep the home. If a son or daughter wants the house, or your family wants to hold it, the balance can be paid off with savings or a new mortgage, and a reverse mortgage can be prepaid at any time. Be careful about assuming the 95 percent purchase rule you may have read about, because HUD’s guide for inheriting a HECM home is written around heirs after a borrower’s death. While your parent’s alive, ask the servicer what they’ll accept before you build a plan on it.
Move back home. Sometimes assisted living is a bridge after a hospital stay and your parent really does come home. If they resume living there before the 12 months are up, the loan keeps going. A short visit home doesn’t reset the clock, though, so don’t count on a weekend at the house to buy another year.
Hand the home back with a deed in lieu. This is the option I’d look at last. It avoids a foreclosure, and it can make sense when there’s no equity left, but it also gives up everything above the loan balance. I worked with a daughter whose estate was in reverse mortgage foreclosure, and at one point she was so worn out she nearly handed the keys back to the lender. She kept going, we sold on the open market for $700,000, about $50,000 over the cash offer she’d first asked about, and her parents’ equity stayed in the family. That was an estate rather than an assisted living move, but the lesson carries over, and you can read how she saved her parents’ equity if you’re feeling the same way.
One thing that isn’t on this list is renting the house out to cover the assisted living bill. It makes sense on a spreadsheet, but a tenant doesn’t make the home your parent’s principal residence, so the loan still comes due. If renting is what you really want, you’d have to pay off the reverse mortgage first.
Paying for Assisted Living While the House Is Still Unsold
The national median for assisted living is now about $6,200 a month, according to CareScout’s 2025 survey, and communities here in Silicon Valley usually run higher, often $8-$12,000 a month or more once care charges are added. Most communities also want a move-in fee up front, which is a real squeeze when your parent’s wealth is sitting in an unsold house.
If your parent has an unused HECM line of credit and the home still counts as their principal residence, they may be able to draw from it, but call the servicer first, because access can end once the loan is called due or the home stops qualifying. A regular home equity line usually isn’t realistic, since the reverse mortgage already holds the lien. Some families use savings or a family loan and pay it back from escrow, and there are short-term elder care bridge loans and programs like Compass Concierge that can sometimes help, so read the current terms carefully. If you want a place to start looking at communities, here are my favorite assisted living communities in Silicon Valley.
Simple Strategy Guide
The Downsizing Guide for Bay Area Seniors
What to keep, what to let go, and how to get your home ready for today's buyers without a costly remodel, so you protect your equity and move on your own timeline.
You're all set. Thanks! The Downsizing Guide is on its way to your inbox. If you don't see it in a few minutes, check your promotions or spam folder.
Three Things to Check Before You List the House
Capital gains. Here’s a trap I want you to see coming: the reverse mortgage payoff doesn’t reduce the taxable gain. Say Mom paid $200,000 for a house that sells for $1.8 million. That’s about $1.6 million of gain before adjustments and selling costs, and her $250,000 exclusion doesn’t come close to covering it. The IRS rules are kinder on the residence test, though. If she lived in the home at least a year out of the five before the sale and she’s physically or mentally unable to care for herself, time in a licensed facility can count toward the two-year residence test. A home sold after death also usually gets a step-up in basis, so on a large gain a CPA should run both scenarios.
Medi-Cal. As I explained in my article on what happens to your home when a parent goes on Medi-Cal, the home can often stay exempt if your parent states an intent to return. Those rules are separate from the reverse mortgage rules, though, and an intent to return won’t stop a loan from coming due. Sale proceeds and reverse mortgage cash can change the picture too, since California’s asset limit came back at $130,000 for an individual in January 2026, and loan money that isn’t spent in the month it’s received can count as an asset. Medi-Cal generally won’t pay assisted living rent either, because even California’s Assisted Living Waiver requires the resident to cover room and board. If Medi-Cal may be part of the plan, please talk to an elder law attorney before you sell.
Legal authority. Find out who can actually sign. If the home’s in a living trust, a successor trustee may be able to step in, and I’ve written about selling a parent’s house in a trust while they’re alive. If it’s not in a trust, you’ll need a durable power of attorney that covers real estate, or possibly a conservatorship if your parent can no longer sign and nothing’s in place.
Capital Gains Calculator
Bought for $180K and worth $2.4M today? See what you'd owe in capital gains tax.
After decades in Silicon Valley, your gain can blow right past the $250,000 and $500,000 exclusions. Plug in your numbers and see your estimated tax bill and how much cash you'll walk away with.
Run My Numbers →What I’d Do in the First 30 Days
If this just landed in your lap, here’s the order I’d take it in. None of it commits your family to selling, and you’ll end up with real numbers instead of guesses.
- Find the loan documents and confirm the loan type (HECM or private), every borrower’s name, any non-borrowing spouse, and the case number date.
- Write down the date your parent moved. That’s the start of the clock, and you’ll want it when you talk to the servicer.
- Call the servicer, tell them what’s going on, ask for a payoff statement, and ask how they’ll handle the occupancy certification. Get the name of the person you spoke with and follow up in writing.
- Call the insurance agent. Many homeowners policies limit coverage once a home sits vacant, and a lapse in required insurance can put the loan in default on its own. Keep paying the property taxes and keep the place maintained too.
- Get a realistic value for the home as it sits today, then compare it with the payoff. That one number usually tells you which of the options above is really on the table.
- Talk to a HUD-approved counselor if you have questions about the loan itself. You can find HECM counseling through HUD, and an elder law attorney and CPA should weigh in on the tax and Medi-Cal side.
If you’d like a second set of eyes on any of this, that’s what I do all day. In a free 30-minute Best Move Strategy Session we can look at the payoff, the value of the house, and the timing together, whether or not your family ends up selling. I’m not an attorney, a CPA, or a loan officer, so I’ll tell you when it’s time to bring one in. You’ve usually got more options than it feels like right now, and my goal is to help you make your parent’s next move the best one yet.
Frequently Asked Questions
Does a reverse mortgage have to be paid off when someone moves to assisted living?
Not right away. On a HECM, the loan can generally be called due once the last borrower has been out of the home for more than 12 consecutive months because of illness, or sooner if the home stops being their principal residence for another reason. If a co-borrower still lives there, the loan usually continues.
Does assisted living count toward the 12-month rule?
Yes. The CFPB names assisted living along with hospitals, nursing homes, and rehabilitation centers. A non-medical move, such as moving in with an adult child, is treated differently, and the CFPB says an absence of more than six months for non-medical reasons means the home is no longer the principal residence when there’s no co-borrower.
Can my parent’s spouse stay in the house if they’re not on the loan?
Possibly. For HECMs with case numbers assigned on or after August 4, 2014, an Eligible Non-Borrowing Spouse who meets HUD’s requirements may be able to stay without repaying the loan after the borrower has been in a healthcare facility for more than 12 consecutive months. Older loans follow different rules, so ask the servicer and consider talking to a HUD-approved counselor or an attorney.
Can we rent out the house to pay for assisted living?
Not without dealing with the loan first. A tenant doesn’t make the home your parent’s principal residence, so renting it out won’t keep the reverse mortgage from coming due. If renting is the goal, your family would generally need to pay off the loan.
What if the reverse mortgage balance is higher than the home’s value?
HECMs are non-recourse, so the borrower and family generally don’t owe more than the home is worth, and FHA insurance covers the shortfall. The CFPB says a sale on a loan that’s due and payable may be allowed at the lesser of the amount owed or 95 percent of the appraised value. Private jumbo reverse mortgages have their own terms, so check the loan documents.
Are adult children responsible for a parent’s reverse mortgage?
Generally no, unless they signed as borrowers. The debt is secured by the home, not by your own assets. If you hold power of attorney or serve as trustee, you may need to act on your parent’s behalf, but that role doesn’t make the loan your personal debt.
Will selling the house affect my parent’s Medi-Cal eligibility?
It can. A home may be exempt, but cash from a sale counts toward the asset limit, which came back at $130,000 for an individual in January 2026. Talk with an elder law attorney before you sell, because the timing and how the money is handled can matter a lot.
Thinking about selling?
Just list with me, I'll do the rest.
Minimum hassle, maximum profit, and a sale on your timeline at a price and terms you'll love.
Let's Get Started →Rather talk now? Call or text 408.413.3087
Senior Friendly Homes in Silicon Valley South
2
3
4
5
6
7
8
9
10
11
12
13
14
15
16
17
18
19
20
21
22
23
24
25