Probate sale · Reverse Mortgage Foreclosure • Built 1965 · Closed February 9
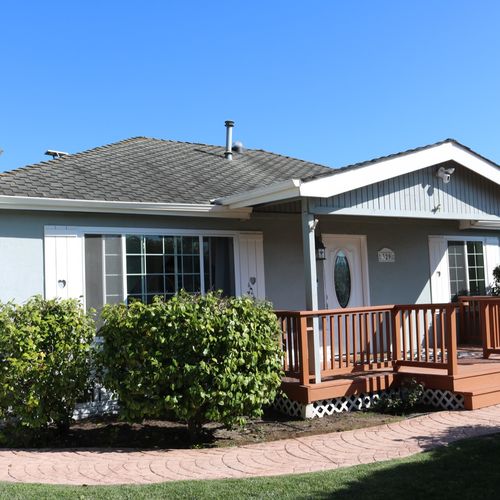
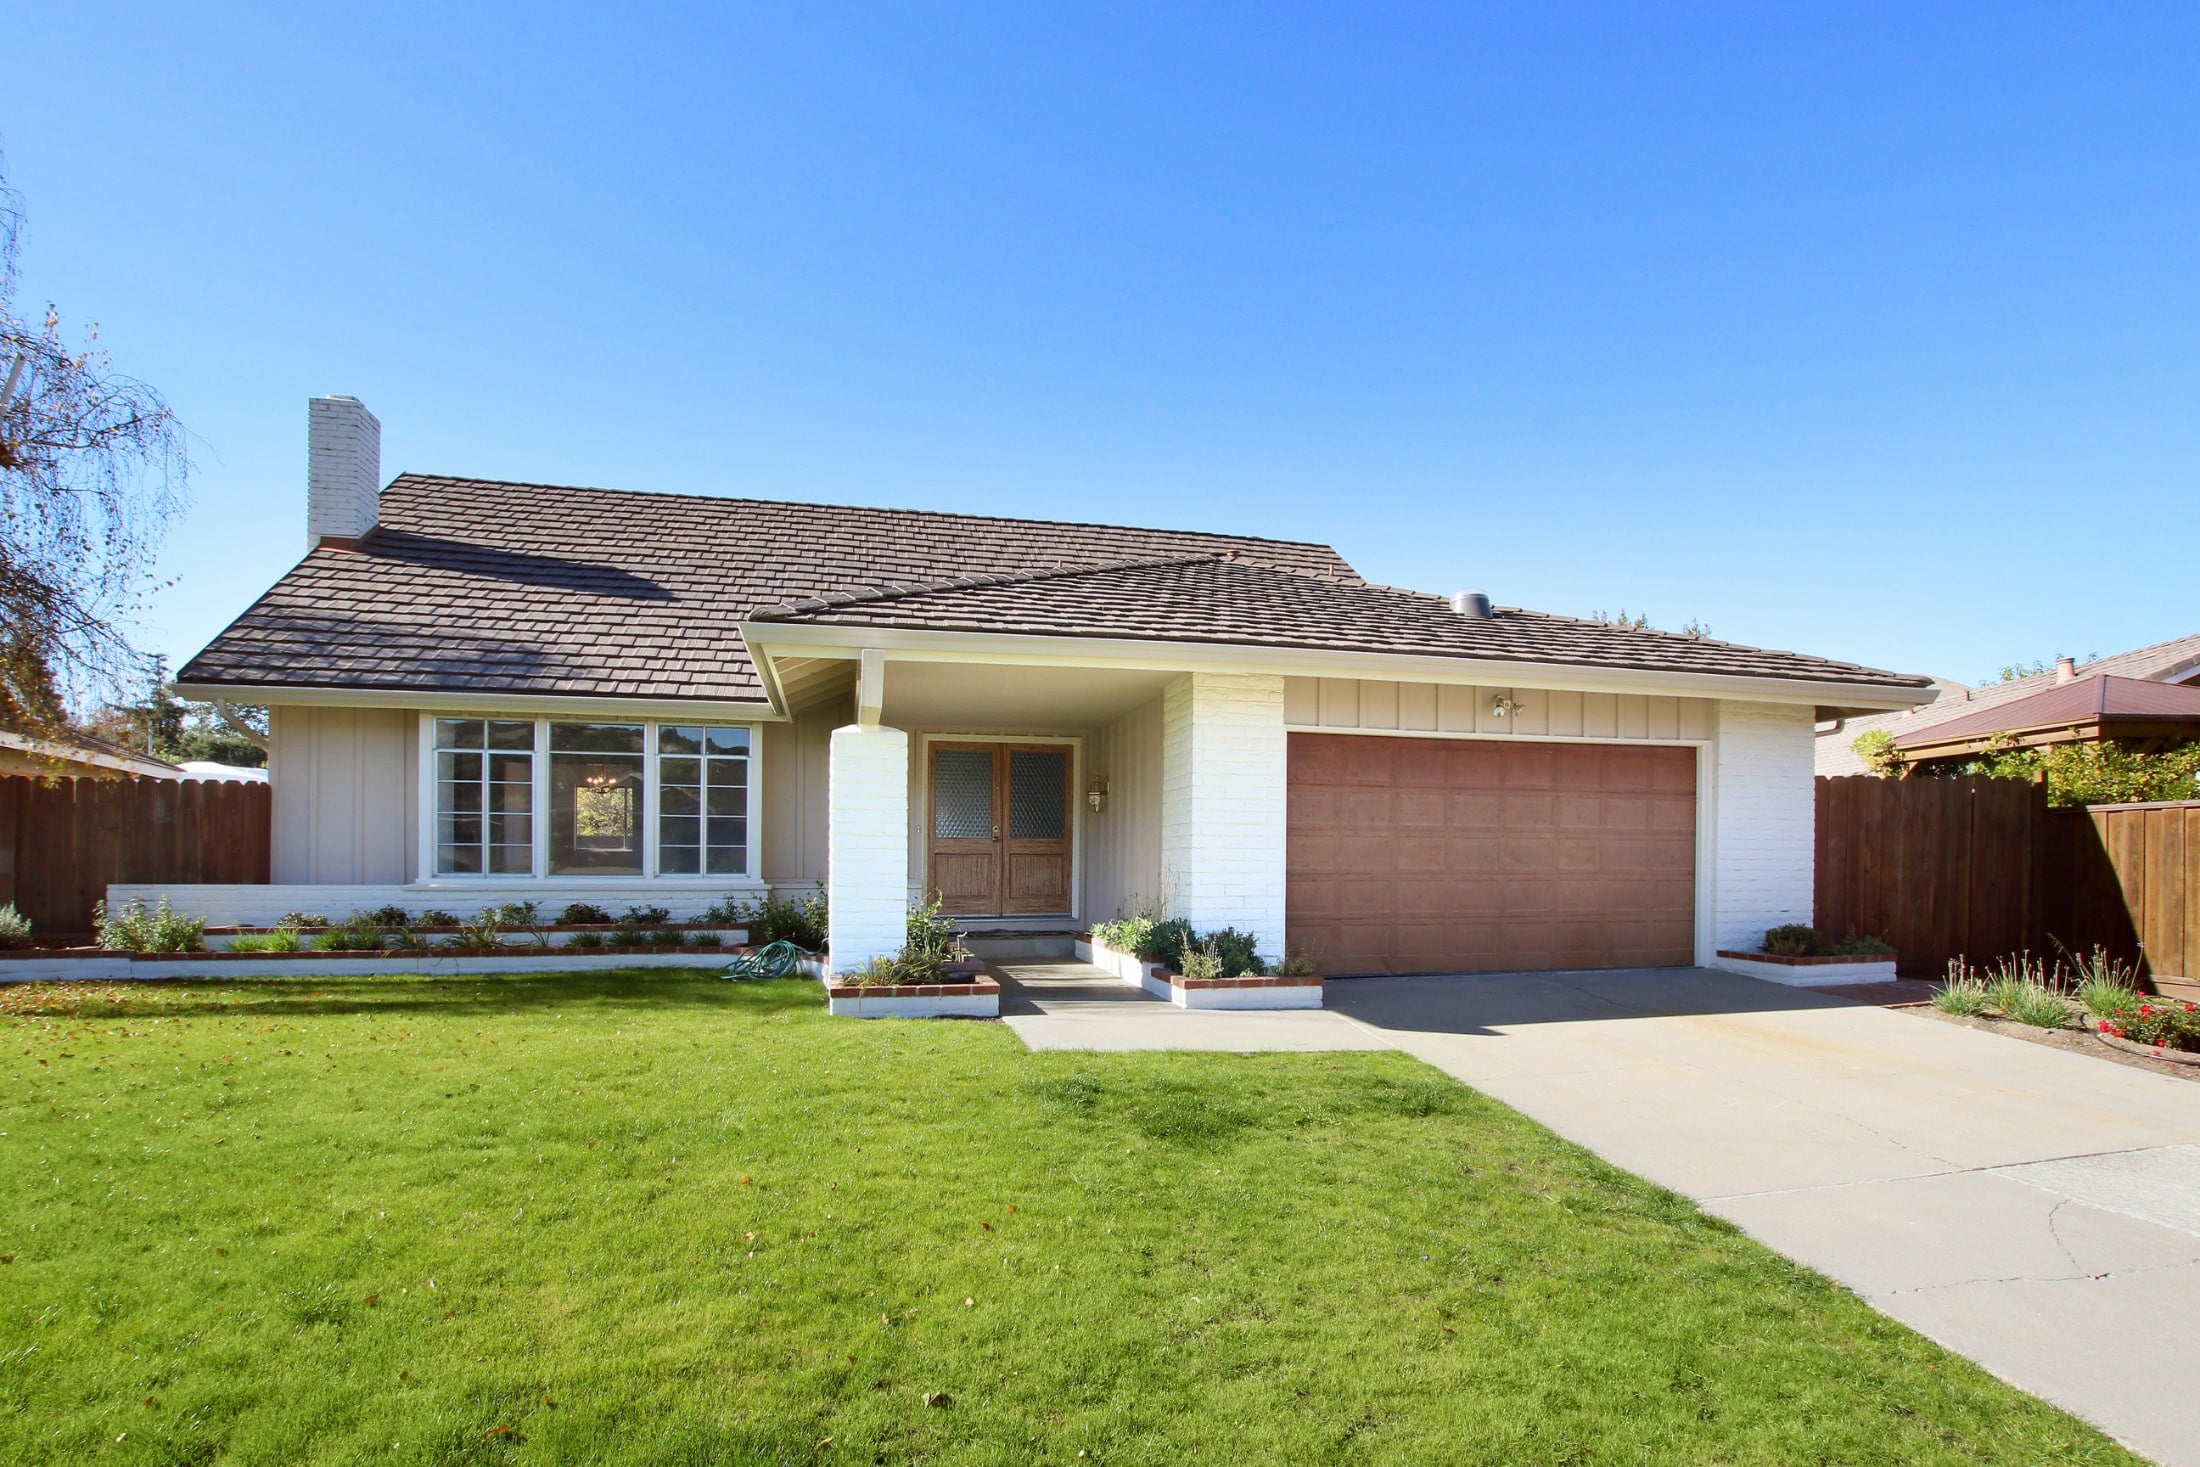
A mother bought this classic home in 1965 and lived in it for the rest of her life. When she passed away, her daughter became executor, inherited a reverse mortgage in foreclosure and a 20-year-old title problem, and still lived in the house. She could have taken a quick cash offer, or simply handed the keys back to the lender. Instead she did the hard part herself: she grieved, sorted through five decades of her parents’ belongings and got the house ready while still living in it. The estate sold for $700,000 cash, the equity her parents built stayed in the family, and she got three weeks of free rent-back so she could say goodbye on her own terms.
The Results
- Her parents’ equity preserved for the estate instead of lost at a trustee sale
- $700,000 sale price, all cash
- 6 offers within five days of the price adjustment, plus a backup offer during escrow
- Closed in about three weeks, ahead of the trustee sale and with no probate court confirmation
- More than $18,000 in prep work, all paid out of escrow at closing
- Free 21-day rent-back so the daughter could move after the proceeds arrived
A Family Home for 52 Years
The owner and her husband bought the house in 1965. He passed away in 2002, and the widow stayed on. After she died, her daughter, the only heir, became executor of the estate. The daughter was living in the house and juggling work and classes. She wanted the house to sell well, but every step of selling it meant letting go of her mother’s home, everything in it, and a lifetime of memories of the only home she’d ever known.
Her first contact with me, in January, was to request a quick cash offer at $650,000. Taking that offer would have been the easy way out, and nobody would have blamed her. Instead she took the time she needed. She grieved, kept up with a reverse mortgage foreclosure that was moving forward whether she was ready or not, and came to terms with the fact that she couldn’t pay off the lender and keep living in the house.
About six months later she made the decision that changed everything for the estate: she would sell on the open market, which ultimately brought in $50,000 more than the cash offer she first asked about. Careful as always with her mother’s estate, she asked someone she trusted to read over my listing agreement before she signed anything. Then the real work began getting the estate and the house ready for market.
As with many estate sales, the hardest part was all the stuff in the house, and here there were more than 50 years of it. That job was hers, and she did it herself, going room by room and deciding what to keep, what to sell and what to toss while still keeping up with work and classes. While she worked through it, we brought in a team to handle the rest of the house: landscaping, flooring, painting and inspections. We pulled up old carpet, waxed the floors, cleared out the garage and made dump runs. While emptying the attic she found her mother’s collector plates and jewelry.
Does your home need some work first?
Let's get it market-ready, and pay for it at closing.
Paint, repairs, flooring and staging, all handled for you through Compass Concierge with nothing out of pocket up front and no contractors for you or your family to manage.
See How It Works →Rather talk now? Call or text 408.413.3087
The Situation
The emotional and material part was only half of it. The estate also had serious financial and legal problems:
- A reverse mortgage in foreclosure. After the owner’s death the loan went into default. The lender stopped granting extensions, and a notice of default was recorded on October 31, 2017. That started the countdown to a trustee sale.
- A 1998 loan that never went away. A $75,000 deed of trust from 1998 had never been released. The title insurer denied the estate’s claim because the policy covered the lender, not the owner.
- No cash for repairs. The house needed paint, flooring, landscaping and a long punch list. Everything had to be paid out of the sale.
- Creditors losing patience. The sewer utility warned it would disconnect service, which would have left the home unable to be sold.
At one point, worn down by all of it, she seriously considered handing the house back to the lender. That would have wiped out the equity her parents had built over half a century, which was virtually all the money she would have to carry her into the next stage of her life. She decided to keep going, and that choice is the reason this story ends the way it does.
How We Saved the Equity Together
She made the decisions that mattered. My job was to clear the obstacles out of her way so those decisions could pay off.
1. Untangled the title before there was a buyer
I opened escrow in June, months before bringing the home to market, so every lien would surface early. I filed the title insurance claim myself. When it was denied, I went to the County Recorder, photographed the records and traced the 2008 refinance line by line. The research showed that a 2007 loan had been paid off in 2008, but a 1998 loan had not. Escrow could then order every payoff and clear the title at closing.
For her, it meant one less problem hanging over the estate, and the probate attorney was glad to see it solved before a buyer was ever involved.
2. Prepared the house with no money up front
I brought in a landscaper, a painter and handyman, a flooring installer and a carpet vendor. Each agreed to be paid out of escrow at closing. I tracked down matching ½-inch red oak to patch the original hardwood floors, and when the replacement sink was out of stock at the local Home Depot, I had one of the crew drive a couple of hours to another to obtain one.
| Work | Cost | How It Was Paid |
|---|---|---|
| Interior and exterior paint, fixtures, lighting, caulking, eave repair, pressure washing and dump runs | $9,302.56 | From escrow |
| Hardwood floor repair | $8,160.40 | From escrow |
| Carpet | $629.00 | From escrow |
| Landscaping: new lawns, planters, trees, hedge pruning, mulch and fence removal | Paid in full | From escrow |
| Termite inspection | $225.00 | From escrow |
| Past-due sewer bill, brought current | $1,687.79 | From escrow |
3. Kept the creditors patient
I updated the sewer utility at every milestone, and it held off on disconnection. The billing office wrote, “Thank you again for working with the utility.” I persuaded the carpet guy to wait for his check at closing instead of filing a lien. I also wrote to the loan servicers and stayed in contact with the foreclosure trustee’s office so they knew a sale was in motion.
4. Marketed around a seller who lived there
The house went on the market at the end of November at $775,000. Marketing included professional photos, two MLS broker tours, five open houses and video walkthroughs. Because the daughter was living in the house, I scheduled every showing around her day, texted her when each buyer arrived and left, and let her know when she could go home.
The first weeks brought plenty of traffic but no offers. On January 3 we cut the price to $749,975, just under the $750,000 search filter. I followed up personally with every open-house visitor and agent who had brought buyers by, and five offers arrived over the next several days, which just goes to show: when the price is right, the market steps up.
Free 9-Step Guide for Heirs
The Guide to Selling an Inherited Property with Ease
Nine steps from the day you inherit to the day you close: settling the debts and utilities, clearing the house without losing the keepsakes, getting a real number on value, knowing when you need a probate attorney and a CPA, and which repairs actually pay you back. Every month you hold the house costs property tax, insurance and utilities, so it pays to have a plan before you start.
You're all set. Thanks! The Guide to Selling an Inherited Property with Ease is on its way to your inbox. If you don't see it in a few minutes, check your promotions or spam folder.
5. Helped her choose the offer that fit her life
Her first question about the offers was whether any of them included a rent-back. I countered the leading offers together. I also screened out any price low enough to require probate court confirmation, which would have meant a hearing, open bidding in court and weeks of delay. The winning buyers paid all cash with no loan or appraisal contingency. They gave her a 21-day rent-back at no cost and wrote her a personal note.
During escrow the buyers’ inspection found water under the house. I traced it to a blocked drain and a missing clean-out cap, and had plumbers fix it within days. Before deciding on any repair request, she asked to talk it through in person, and we did. On signing day the reverse mortgage payoff still hadn’t arrived. I called the foreclosure trustee directly. The payoff came at 10:47 that morning, she signed at 1 PM, and the sale closed the next day.
6. Stayed with her after closing
Selling the house was only part of the job. During the rent-back I sent the same crew that had worked on the house to help her move. On March 2 I came back with plywood and a drill to patch a hole in the floor, and to say goodbye to the house with her. When I suggested it, she warned me there might be tears, and I told her that was exactly what I was there for.
In the months that followed, I lined up movers to bring her things out of storage, filmed a walkthrough of her new place and kept watching listings for her. Bringing the crew back for those moves wasn’t part of the listing agreement, and she knew it, which made the help mean that much more to her. Looking back, we agreed there had been plenty of tears and stress, but some real fun along the way too.
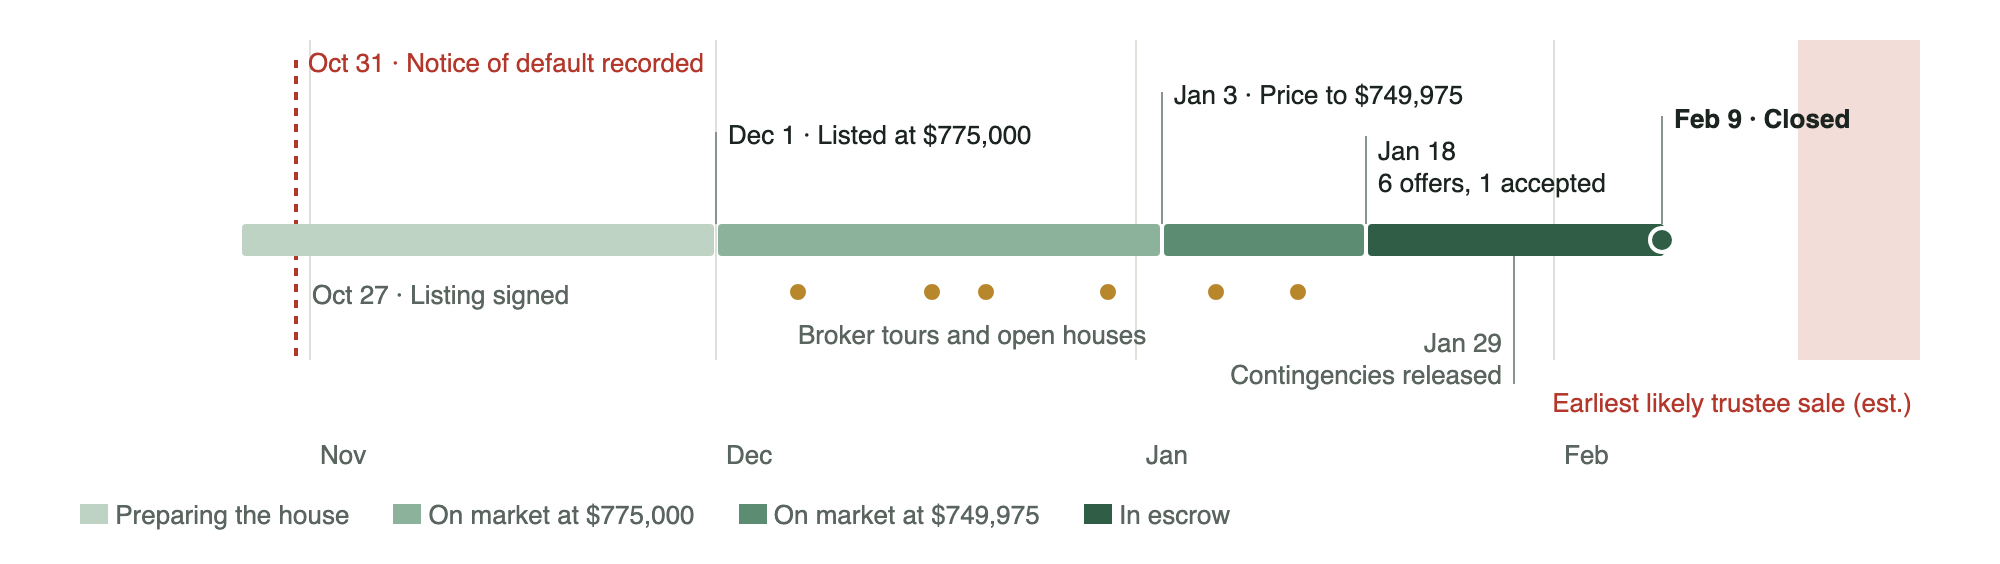
Timeline: First Call to Final Goodbye
Prepare
- January: The daughter asks for an instant cash offer at $650,000. That request leads to our first conversation.
- March–April: Title claim denied. County records researched and the old loan identified.
- June: Escrow opened with no buyer yet.
- September: Garage sale, movers and storage. Probate appraisal of $710,000.
- October 27: Listing agreement and seller disclosures signed.
- October 31: Notice of default recorded on the reverse mortgage.
- November: Painting, flooring, carpet, landscaping and termite inspection. Photos taken November 28.
Market
- Late November: On the MLS at $775,000. First showings begin November 30.
- December 7 and 21: MLS broker tours.
- December 17 to January 13: Open houses.
- January 3: Price reduced to $749,975.
The Offers
| Offer | Received | Terms | Outcome |
|---|---|---|---|
| Investor | January 14 | All cash, with proof of funds. Price too low: accepting it would have required probate court confirmation. | Countered January 18. The investor walked away; his new position was $5,000 lower, plus $10,000 held in escrow until the seller moved out, instead of a rent-back. |
| Owner-occupant buyer | January 14 | Higher than the investor’s offer; financed rather than cash. | Not chosen. |
| Cash buyer | January 16 | All cash, with proof of funds. | Countered January 18. The buyer countered back January 19, after another offer had been accepted. |
| Military family | January 18 | Came with a letter to the seller. | Not chosen. |
| Winning buyers | January 17 | $700,000 all cash, $21,000 deposit, no loan or appraisal contingency, with a personal note to the seller. The seller countered at $725,000 with a free 21-day rent-back and a 10-day inspection period. The buyers came back at $700,000 and kept the rent-back. | Accepted January 18. Closed February 9. |
| Backup offer | January 22 | $700,000 with a $575,000 loan and a 45-day close. The seller countered at $720,000 with a 28-day close and a free 21-day rent-back. The buyers accepted everything but the price, since their loan approval topped out at $700,000. | Signed as a backup January 26. Not needed. |
Negotiate
- January 14–18: Five offers, including three all-cash offers. Counters sent and an all-cash offer accepted.
- January 22: Buyers’ home inspection. Backup offer received.
- January 29–30: Buyers release all contingencies.
Close and Move On
- February 8: Payoff demand arrives in the morning. The executor signs in the afternoon.
- February 9: Closed. Every lien, vendor and utility paid from the proceeds.
- February–March: Rent-back and move-out with help from the crew.
- March 2: Floor patched, and a last goodbye to the house.
- April: Belongings moved from storage into her new home.
The Takeaway: An Estate Sale Is a Family’s Story
On paper, this was a probate sale against a foreclosure deadline. Clearing the title early, paying for the prep work out of escrow and keeping every creditor informed made a fast, clean sale possible.
But the person who saved this estate’s equity was the daughter. She could have taken a quick $650,000 cash offer or handed the house back to the lender, and either choice would have been understandable. Instead she grieved, sorted through 52 years of her parents’ life while still living in the house, and stayed with a process that was hard on her from start to finish. The plan had to work for her as well as the estate: showings around her schedule, a rent-back so she could move after the money arrived, and someone beside her when it was time to say goodbye. Her parents’ equity stayed with the family. Even the sewer utility’s billing office, which had threatened to shut off service, wrote at closing: “Congratulations!! We are all winners!!”
“You really are the REALTOR® of choice…and the best friend a girl could have.” -The owner’s daughter and executor
Free Seller Strategy Session
Before we talk money, let's talk about you.
The biggest financial wins in a move happen long before a home hits the market, and they start with understanding your situation. In 30 minutes we'll talk through what's changing, who's involved, and what you need this move to do for you, then map out a plan that gets you there with a clear financial advantage.
Book My Strategy Session →
Senior Friendly Homes in Silicon Valley South
2
3
4
5
6
7
8
9
10
11
12
13
14
15
16
17
18
19
20
21
22
23
24
25