More and more of the families I work with are talking about living together again. Sometimes Mom moves into the spare room at her son’s place in Campbell, and sometimes she sells the house she’s owned for 40 years and builds an ADU on her daughter’s property so she can have her own front door with the grandkids a few steps away. According to Pew Research Center, about 22% of Americans lived in a multigenerational household in 2024, and in a market as expensive as ours it’s easy to see why. Done well, this kind of move gives a parent independence with family close by and can make real financial sense for everyone. Done without a plan, especially when the money from the parent’s house goes into the child’s property, it can strain relationships and create legal and tax problems nobody saw coming.
This is what I walk through with families before anyone breaks ground or signs anything. It’s part of my bigger guide to moving from Silicon Valley to be near family, and if you haven’t had the first conversation with your parents yet, my article on how to talk to your aging parents about selling the family home is a good place to start.
Key Takeaways
Summary: Moving in with your adult children or into an ADU on their property can be a wonderful arrangement, but the ADU belongs to whoever owns the land, even if you paid for it. Treat the money like the major financial decision it is: decide whether it’s a gift, a loan, or an ownership interest, check the Medi-Cal and Prop 19 rules, plan the timeline around the sale of your home, and put a written family agreement in place so everyone, including siblings, is treated fairly.
From my practice: One property I sold for a conservator had a two-bedroom main house, a one-bedroom rear cottage and a studio in the attic, all on one single-family lot. I valued it on income as well as comps because a buyer could use it as a family compound, a rental, or live in one unit and rent the others, and I listed it on the MLS twice so both buyer pools would find it. It sold for $920,000 all cash, with the first offer arriving eight days after it went live.
Free 2026 Checklist for Families
The Parent's Home Transition Plan
When Mom or Dad needs assisted living or memory care, it usually happens faster than anyone planned. This checklist keeps the house from becoming one more crisis.
- Every step in order, from the first conversation to the sale
- The legal paperwork and paying for care
- The cleanout, the sale of the house and the taxes
You're all set. Thanks! The Parent's Home Transition Plan is on its way to your inbox. If you don't see it in a few minutes, check your promotions or spam folder.
The Most Common Living Arrangements
Most families end up in one of a few setups. Each one can work beautifully, and each has its own trouble spots you’ll want to think through before anyone commits.
| Arrangement | Pros | Watch out for |
|---|---|---|
| Parent moves into the child’s existing home | Lowest cost and fastest | Privacy, stairs, and household dynamics |
| Junior ADU (JADU) carved out of the child’s home | Up to 500 square feet with its own entrance, usually cheaper and faster than a detached unit | Shares walls with the main house, and the child still owns it |
| Parent funds a new detached ADU on the child’s lot | Independence with family nearby, and the ADU adds value to the child’s property | The child owns it, and the arrangement needs clear documentation |
| Parent and child buy a home together | Room for both, possibly with an ADU or in-law suite | Co-ownership terms, financing, and what happens on a sale or death |
If you’re leaning toward buying together, the co-ownership terms matter as much as the house itself. How title is held, who’s on the loan, and what happens when one of you passes away or wants out should all be in writing before you close escrow.
When the Parent Pays for the ADU
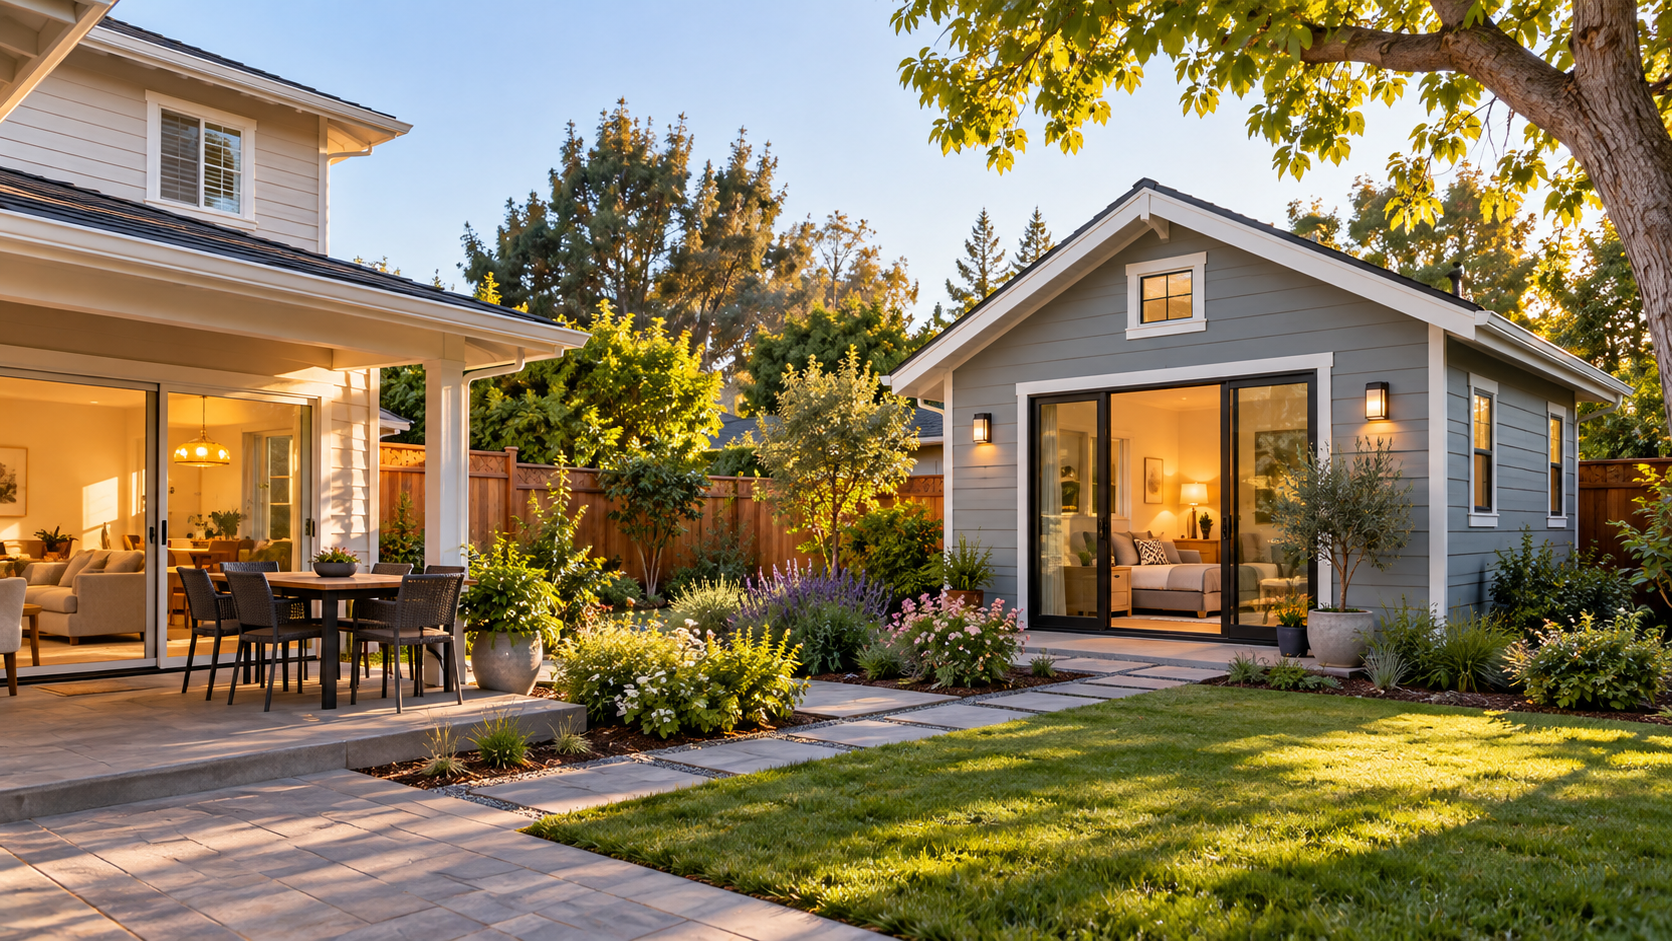
Here’s the situation I see most often. Say a mother sells her San Jose home and spends $350,000 building a detached ADU in her daughter’s Roseville backyard. Legally, that ADU becomes part of her daughter’s property, the same way a new garage or pool would. Mom has a lovely little home of her own, but she doesn’t own it, and that raises a handful of questions every family should answer up front:
- Is it a gift or a loan? If it’s a gift, anything over the $19,000 annual exclusion to one person in 2026 means filing IRS Form 709. With the lifetime gift and estate tax exemption at $15 million per person in 2026, tax is rarely due, but the return still has to be filed. If it’s a loan, document it with a promissory note, a reasonable interest rate, and ideally a recorded deed of trust so it holds up later.
- What about the other children? If Mom’s estate will be split equally, a $350,000 benefit to one child may need to be accounted for in her trust. This is exactly where a lot of sibling conflict starts, so it’s worth talking through openly while everyone’s getting along.
- What if the daughter sells, divorces, or runs into financial trouble? Mom’s home is now tied to her daughter’s property, her marriage, and her creditors.
- What if Mom needs Medi-Cal later? California reinstated the Medi-Cal asset limit on January 1, 2026, at $130,000 for a single person, and transfers made within 30 months before nursing home admission can trigger a penalty period. A home is generally an exempt asset, but the cash from selling one isn’t, so talk to an elder law attorney before the money moves.
Families handle these questions with a written agreement, a recorded interest in the property, or other legal structures. Choosing the right one is squarely a job for an estate planning attorney, and it’s far easier to set up before the money moves than to untangle afterward.
Free 2-minute family assessment
Worried about Mom and Dad? See If It's Time to Have The Talk.
Answer a dozen quick questions about what you've noticed, the house itself, and who in the family is involved. You'll get an honest read on how urgent things really are and a plan for starting the conversation without a family fight.
Take the Quiz →Rather talk now? Call or text 408.413.3087
Building an ADU
California has made ADUs dramatically easier to build over the past several years. Under state law, once a city has a complete application it has 60 days to approve or deny the permit (the state’s HCD ADU resources lay out the rules), and many cities, including San Jose, now offer preapproved ADU plans that can shave time off design. Even so, a detached ADU commonly takes many months from first sketch to move-in, and in the Bay Area the cost often runs several hundred thousand dollars depending on size, site work, and utility connections. Plan the timeline so the parent’s current home doesn’t have to be sold before the ADU is ready, or line up a short-term rental in between. For more on ADUs as a housing option for older adults, see my article on ADUs as an aging-in-place solution.
Building an ADU is new construction for property tax purposes, so the child’s assessed value goes up by the value the ADU adds while the main house keeps its existing assessed value. That bill goes to the child as the owner, which is why it belongs in your family agreement. While you’re at it, design the ADU for aging from day one: no steps at the entry, a curbless shower, wide doorways, lever handles, good lighting, and room for a caregiver someday. Building those in now costs far less than retrofitting later, and my article on aging-in-place remodel costs breaks down what those features typically run.
A real example: Lot size and zoning decide whether an ADU is even possible. On an inherited property on a flat 8,100-square-foot lot zoned R-1-6, the disclosure package included ADU and SB 9 research, and we marketed the lot dimensions along with the house because there was room for a detached ADU. If you’re thinking about moving onto a child’s property, the same homework applies: check the zoning, the setbacks, and what the city will permit before anyone signs a contract.
Free 3-minute decision check
Stay, downsize, or move away? Find out which one costs you the least.
For longtime Bay Area owners, the wrong call can cost six figures in taxes, remodeling, or years of higher living costs. Answer a dozen quick questions and see all three paths side by side, with a rough dollar figure for what each one would cost you or free up.
See My Best Path →Rather talk now? Call or text 408.413.3087
Questions for a Family Agreement
I always encourage families to put this in writing, even when everyone gets along beautifully. Especially then, actually, because it’s a lot easier to agree on the hard stuff while everyone’s happy. Your agreement should answer these questions:
- Who pays for what, including utilities, the property tax on the ADU’s added value, insurance, and maintenance?
- Is the parent’s contribution a gift, a loan, or an ownership interest?
- What happens if the child needs to move or sell?
- What happens to the parent’s contribution if the parent passes away or moves to assisted living?
- What care, if any, is the family expecting to provide as needs change, and when would outside care or assisted living make sense?
- How will the arrangement be treated fairly among the other siblings?
- How will everyone protect privacy and independence on both sides of the backyard?
Selling the Silicon Valley Home
For most families, the sale of the parent’s home is what pays for the move. If you’re 55 or older and buy or build a replacement home in California that you own and live in, Prop 19 may let you take your low property tax base with you, and my Prop 19 base-year transfer guide walks through how that works. Building an ADU on your child’s lot isn’t buying a replacement home of your own, though, so the base-year transfer generally won’t apply to that arrangement. On the income tax side, the federal home sale exclusion still shelters up to $250,000 of gain ($500,000 for a married couple) if you’ve owned and lived in the home for two of the last five years. Longtime Silicon Valley owners often have gains well beyond that, so read my guide to capital gains tax when selling your home and sit down with your CPA before you list. For the full plan, including timing the sale, see my guide to moving from Silicon Valley to be near family.
Is This the Right Move for Your Family?
Over more than 23 years and 460+ closed transactions, I’ve helped a lot of families through moves like this, and the ones that go best are the ones where everybody talks openly about money, care, and expectations before the first check is written. If you’re weighing a move in with your kids or into an ADU on their property, I’m happy to help you think through the sale of your home and the timing so the new place is ready when you are. For the bigger picture on selling a longtime family home and moving somewhere smaller, start with my Bay Area downsizing guide, and if care needs are part of the picture, my guide to paying for in-home care in Silicon Valley is a good next read.
Frequently Asked Questions
Who owns an ADU built on my child’s property?
Whoever owns the land, which is usually your child, even if you paid to build it. Families often document the parent’s contribution as a gift, a loan secured by a deed of trust, or another structure set up by an estate planning attorney.
Do I owe gift tax if I pay for an ADU on my child’s property?
Usually not, but you’ll likely need to file. Gifts over $19,000 to one person in 2026 require a federal gift tax return (Form 709), and tax is only owed after you’ve used up the $15 million lifetime exemption. The gift can still affect Medi-Cal planning and fairness among siblings.
Can paying for my child’s ADU affect my Medi-Cal eligibility?
It can. California reinstated a $130,000 asset limit for a single person in 2026, and transfers made within 30 months before nursing home admission can trigger a penalty period. Talk to an elder law attorney before moving the money.
Does building an ADU raise property taxes?
Yes. The ADU is new construction, so the property’s assessed value increases by the value the ADU adds, while the existing home keeps its current assessed value.
Can I use Prop 19 if I move into an ADU on my child’s lot?
Generally no. The Prop 19 base-year transfer applies when you buy or build a replacement home that you own and live in as your primary residence, and an ADU on your child’s lot belongs to your child.
How long does it take to build an ADU in California?
Cities must approve or deny a complete ADU application within 60 days, but a detached ADU commonly takes many months from design to move-in, so plan the sale of your current home accordingly.
What’s the difference between an ADU and a JADU?
An ADU can be attached or detached and has its own kitchen and bathroom. A junior ADU, or JADU, is up to 500 square feet carved out of the existing home and can share a bathroom with the main house.
Simple Strategy Guide
The Downsizing Guide for Bay Area Seniors
A simple plan for getting from the house you're in to the home you want next.
- What to keep and what to let go
- How to get the house ready without a costly remodel
- How to protect your equity and move on your own timeline
You're all set. Thanks! The Downsizing Guide is on its way to your inbox. If you don't see it in a few minutes, check your promotions or spam folder.
Senior Friendly Homes in Silicon Valley South
2
3
4
5
6
7
8
9
10
11
12
13
14
15
16
17
18
19
20
21
22
23
24
25