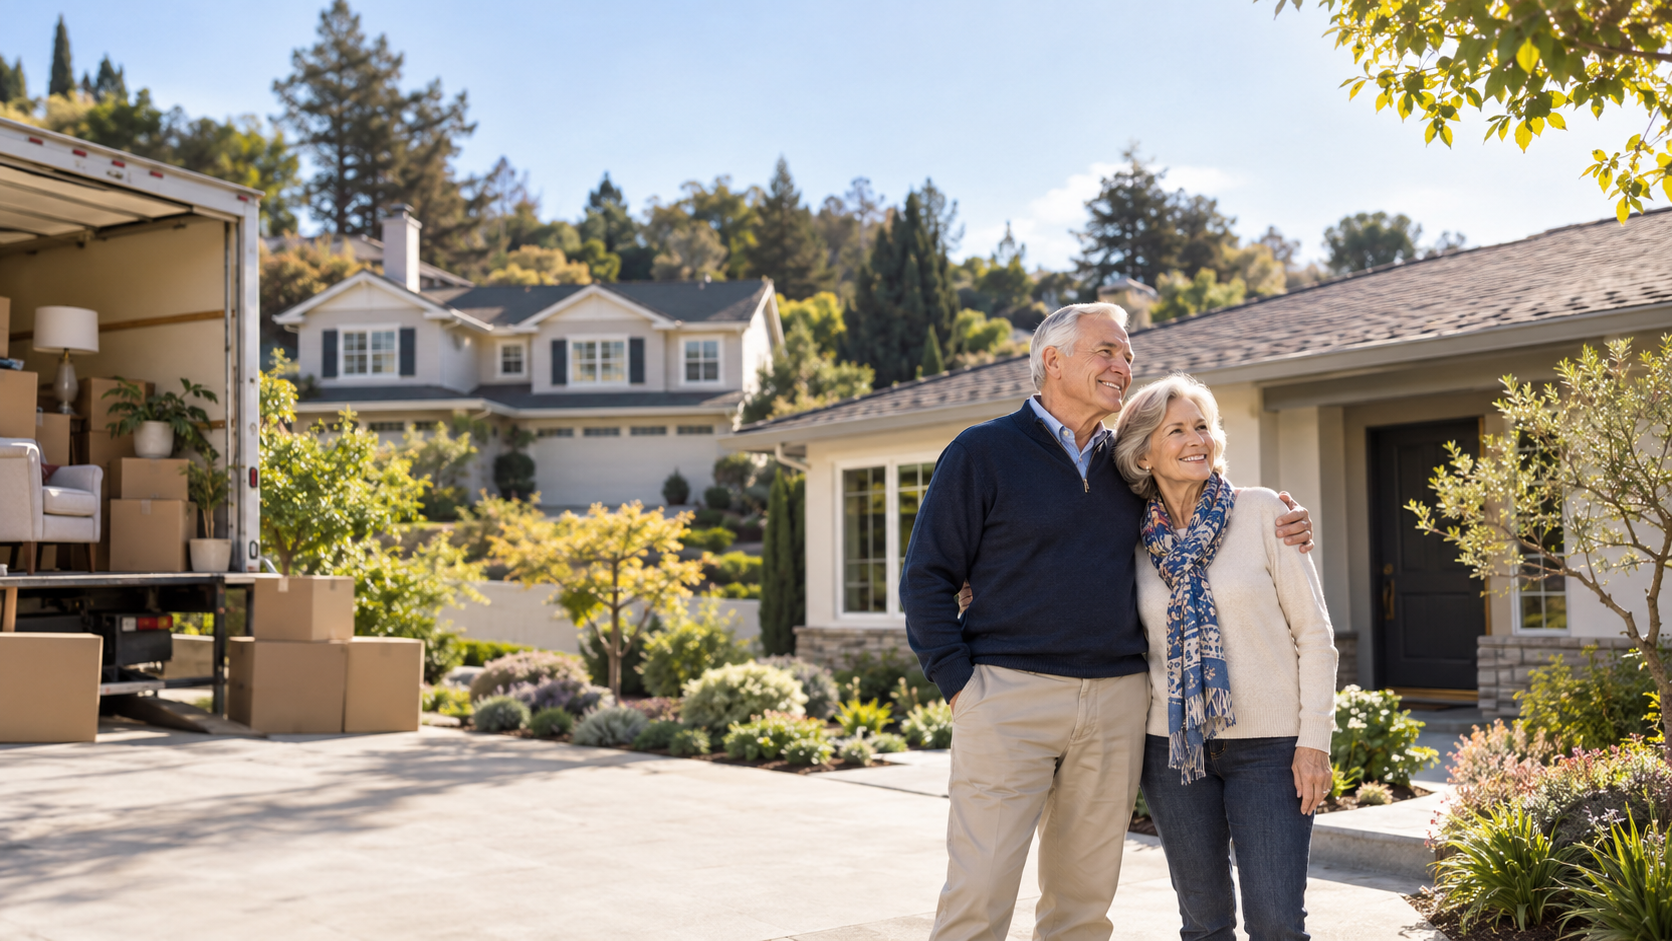
The single biggest source of stress for older homeowners who want to downsize is the sequence. Sell first, and you may have to move twice, rent in between, and put your furniture in storage at 78 years old. Buy first, and you need to come up with a down payment while most of your wealth is tied up in the house you still live in. I hear some version of “I can’t sell until I know where I’m going, and I can’t buy until I’ve sold” in almost every first meeting with a downsizing couple. The way I explain it is that each path wins on something different. Buying first is the easiest way to do it, because you move once and sell an empty, prepared house. Selling first is usually much cheaper, because your sale proceeds fund the next home and you don’t need a bridge loan or HELOC to carry two properties, but it can mean moving twice, which most people would rather avoid. This article lays out how to make either path work in Silicon Valley, and it’s part of my Silicon Valley downsizing guide. I’m a REALTOR®, not a lender or tax advisor, so please run the specific numbers by yours.
Key Takeaways
Summary: Buying first is the easiest way to downsize, because you move once and sell your current house empty and staged. Selling first is usually much cheaper, since no bridge loan is needed, but it can mean moving twice unless you negotiate a rent-back. A HELOC, bridge loan, securities-based line, or buy-before-you-sell program can make buying first work, and retirees can often qualify based on assets.
Why Buying First Is the Easiest Path
When you sell a home you’re still living in, you’re showing it with your furniture, your routines, and your 40 years of belongings, and you’re scrambling to pack while in escrow. When you move first, I can have the house cleaned out, lightly refreshed, and staged, and buyers see it at its best. In my experience the better presentation can win back some or all of what the financing costs, though not always, which is why selling first is still usually the cheaper route. It’s also much easier on the people moving.
The order matters more for downsizers than for a young family moving up, because it isn’t only about money. Moving twice in a year is exhausting at 72 in a way it wasn’t at 42, and the clean-out of a 30-year home is a project all by itself. On the other hand, most of my clients own their homes free and clear or close to it, which opens financing options a younger buyer wouldn’t have. The right order comes down to three numbers: how much cash you can get to before your house sells, what the new place will cost, and how long you can comfortably carry two properties. This sequencing problem is a big part of why downsizing can feel impossible.
Buy First vs. Sell First at a Glance
| Buy first | Sell first | |
|---|---|---|
| Cash certainty | You’re estimating your sale price | You know exactly what you netted |
| Number of moves | One | Possibly two, unless you negotiate a rent-back |
| Strength as a buyer | Strong with a HELOC, bridge loan or cash, weak if contingent | Strong, non-contingent offer with cash in hand |
| Financing cost | HELOC or bridge loan interest and fees while you own both homes | Usually none, since your sale proceeds fund the purchase |
| Carrying costs | Two sets of taxes, insurance and loan payments until the old home sells | Rent or rent-back costs, if any |
| Prep and staging | Move out, then prep and stage an empty house | You may still be living in the home while it’s shown |
| Biggest risk | The old home takes longer to sell or sells for less | Not finding the right next home in time |
Free 3-minute decision check
Stay, downsize, or move away? Find out which one costs you the least.
For longtime Bay Area owners, the wrong call can cost six figures in taxes, remodeling, or years of higher living costs. Answer a dozen quick questions and see all three paths side by side, with a rough dollar figure for what each one would cost you or free up.
See My Best Path →Rather talk now? Call or text 408.413.3087
Your Options
| Option | How it works | Watch out for |
|---|---|---|
| Home equity line of credit (HELOC) | Borrow against your current home for the down payment or full purchase, and pay it off when the house sells | It has to be opened before you list, because lenders generally won’t open one on a home that’s for sale. Start months ahead. |
| Bridge loan | A short-term loan secured by your current home, designed for this situation | Higher rates and fees than a HELOC, and terms vary widely, so get quotes from more than one lender |
| Securities-based line of credit | Borrow against an investment portfolio without selling it | Market declines can trigger a margin call. Talk to your financial advisor. |
| Cash from savings or investments | Pay for the new home outright and replenish from the sale | Selling investments can create taxable gains of their own |
| Buy-before-you-sell programs | A company helps you buy first and sells your home afterward | Read the fees and the guaranteed price terms carefully |
| Contingent offer | Your offer depends on selling your current home | Sellers in competitive segments usually reject these, though they can work for senior communities, new construction and slower segments |
Qualifying on Retirement Income
Many retirees assume they can’t get a mortgage because their income is modest. Lenders can often count retirement account and investment assets through asset-based underwriting, and Social Security and pension income count as well. A couple with a paid-off $2.4 million home and $1.5 million in retirement accounts is usually a strong borrower, even with modest monthly income. Talk to a lender early, because the preapproval shapes everything else. Age by itself isn’t a legal reason to deny you credit under federal fair lending rules, although lenders will still look at income and ability to repay.
Here’s how lenders actually do the math under Fannie Mae’s rules for using retirement assets as income. They start with the balance of your 401(k) or IRA and subtract any early-withdrawal penalty, plus the money you’re using for the down payment, closing costs, and reserves. Whatever is left gets divided by the loan term, usually 360 months. So if you have $1.2 million left after those deductions, that account alone shows about $3,300 a month in qualifying income, on top of Social Security and any pension. If the person whose assets are being used is 62 or older at closing, the loan can go up to 80 percent of the price instead of 70 percent. You need unrestricted access to the funds, which is why this works best for downsizers who are already past 59½.
From my practice: One seller in her eighties couldn’t buy her next home without the equity in her current one. We wrote a full-price cash offer on her next home contingent on her sale, then timed both escrows with the same title company so her proceeds moved straight from one to the other. She had a 10-day free stay after closing, moved once, and never needed a bridge loan.
What Buying First Costs a Downsizer: A Worked Example
Let’s say you own a Cupertino home worth $2.4 million free and clear, and you’re downsizing to a $1.1 million single-level home. You open a $700,000 HELOC before listing (if your lender’s limits allow it), add $400,000 from savings, and make a cash offer, which puts you in the strongest position a buyer can be in. At an assumed 8 percent variable rate, interest on that HELOC runs about $4,700 a month. If moving, prep, marketing, and escrow take five months, you’re out roughly $23,000 in carrying costs. Selling a vacant, staged house only has to get you 1 percent more on a $2.4 million sale to cover that, and you also skip moving twice, paying short-term rent, and renting storage. If you sold first instead, that $23,000 would stay in your pocket, which is the main reason selling first is usually the cheaper path. HELOC rates change, so get a current quote before you run your own numbers.
A Sample Sequence
- Three to six months ahead: meet with a lender and open a HELOC if that’s the plan. Start sorting belongings.
- Two to three months ahead: tour neighborhoods and narrow down the kind of home that fits.
- Buy: make a strong, non-contingent offer on the new home, funded by the HELOC or bridge loan plus savings.
- Move: take what fits the new home, and schedule the estate sale or donation pickup for the rest.
- Prepare: cleanout, paint, floors, and staging on the now-empty house, usually four to six weeks.
- Sell: list, sell, and pay off the HELOC or bridge loan at closing.
A real example: One set of longtime owners had already bought their next home before we listed, and that changed everything about the sale. They could test the price as a Compass Private Exclusive in the fall, fix the health and safety items, and wait to launch on the MLS in January, when the data said to list. The house sold for $2,050,000 with no contingencies and a 21-day close, plus a free 10-day stay afterward so they could move once, on their own schedule.
Selling First: The Cheaper Path
Selling first is usually the less expensive way to downsize. Your sale proceeds pay for the next home, so there’s no bridge loan or HELOC interest and no second set of property taxes and insurance, and you shop with an exact number in hand and a non-contingent offer. The tradeoff is the move itself. Without a rent-back you may end up moving twice, into a rental and then into the new home, with your furniture in storage in between, and most of my clients would rather avoid that. A rent-back is how we usually solve it. As the seller, you negotiate to stay in the house for a period after closing, often up to 60 days, which gives you time to find and close on the next home. The buyer’s loan terms can limit how long a rent-back can be, so it has to be part of the negotiation from the start. Another option is to move into a short-term furnished rental, particularly if you’re considering renting longer term anyway. See should you rent or buy after selling.
The 60-day limit isn’t arbitrary. Most buyers use conventional loans, and the standard deed of trust requires them to move into the home within 60 days of closing, so a longer rent-back can conflict with the buyer’s loan. That’s why I raise it at the very beginning of negotiations rather than after we’re in contract.
The paperwork changes with the length of the stay, too. For 29 days or less, California REALTORS® typically use a Seller in Possession addendum, which is treated as a license rather than a tenancy. For 30 days or longer, a Residential Lease After Sale is common, and that creates a landlord-tenant relationship with deposit rules and possibly local tenant protections. In practice, a 30 to 60 day rent-back covers the timing for a lot of my clients who sell first, especially if we’ve already started looking before the house lists.
Simple Strategy Guide
The Downsizing Guide for Bay Area Seniors
What to keep, what to let go, and how to get your home ready for today's buyers without a costly remodel, so you protect your equity and move on your own timeline.
You're all set. Thanks! The Downsizing Guide is on its way to your inbox. If you don't see it in a few minutes, check your promotions or spam folder.
Prop 19 and the Order of Transactions
If you’re 55 or older and plan to use the Prop 19 base-year transfer, you can buy the replacement up to two years before or after selling. If you buy first, the replacement generally must be no more than 100 percent of your original home’s sale value to carry over your assessed value in full. Since most downsizers are buying less expensive homes, that’s rarely an issue. If you sell first, the limit rises: according to the Board of Equalization, a replacement bought within the first year after the sale can be worth up to 105 percent of the sale price, and within the second year up to 110 percent. Go over the limit and the difference is added to your transferred base rather than disqualifying you. You can use the transfer up to three times, and you file the claim (form BOE-19-B) with the assessor in the county where the new home is, within three years.
Here’s an illustrative example. Say you sell your Cupertino home for $2,600,000, your current assessed value is about $450,000, and you buy a $1,400,000 condo in Aptos. Under Prop 19 you’d generally carry your roughly $450,000 base to the new home instead of being assessed at $1,400,000, which at a property tax rate around 1 percent is the difference between roughly $4,500 and $14,000 a year, every year. The two-year window is what lets you buy first without giving that up. My Prop 19 explainer for seniors has more examples. See the Prop 19 base-year transfer. For the full planning picture, see my complete guide to downsizing in Silicon Valley.
Downsizing and Capital Gains: What Buying First Means for Taxes
If you’ve owned and lived in your home for at least two of the last five years, IRS rules let you exclude up to $250,000 of gain, or $500,000 for a married couple filing jointly. Buying first and moving out doesn’t cost you that exclusion as long as you sell within three years of moving out. A surviving spouse can generally still use the $500,000 exclusion if the home sells within two years of the spouse’s death.
Most longtime Silicon Valley owners have gains well beyond those limits, so how you fund the purchase matters. If you sell appreciated stock for the down payment, you create a second taxable gain, and a securities-based line of credit avoids that. In California, a surviving spouse may also get a full step-up in basis on community property, which can change whether it’s smarter to sell or hold. Have your CPA run these numbers before you choose a financing route.
Choosing the Right Home When You Downsize
The downsized home should work for the next 15 or 20 years, not just the next two. Look for a single-level layout or a primary bedroom and full bath on the main floor, a no-step entry, wide hallways and doorways, and a walk-in shower or room to add one. Think about how close you’ll be to your doctors, your family, and the places you go every week, since driving less is usually part of the plan eventually.
For condos, California law requires HOAs to do a reserve study at least every three years, so read it and check whether the reserves are adequately funded before you commit. As a Certified Aging in Place Specialist, I walk through every home with these questions in mind.
Mistakes Downsizers Make When Buying First
The most common one is waiting until the house is listed to open the HELOC, at which point most lenders won’t do it. The second is shopping before getting preapproved with asset-based underwriting, so you find the right home and can’t move fast enough to get it. Others are underestimating how long the cleanout takes after 30 or 40 years in a home, and buying a replacement that costs more than your sale price when you’re counting on the Prop 19 transfer to keep your property taxes low.
What I See With Downsizing Couples
A pattern I see a lot: a couple in their mid-seventies in a two-story Almaden home they bought in 1991. She’s ready to go and has already toured three single-level homes in Los Gatos. He’s not sure, and what he’s really worried about is ending up in a rental for six months with their furniture in storage. Their daughter, who lives in Willow Glen, wants them close and is the one emailing listings at midnight.
What usually works for a family like this is getting the house ready and lining up the purchase search at the same time. If they have the cash or a HELOC already open and the right place shows up, they buy first and we prep the old house after they’ve moved, which usually makes it show and sell better. If they don’t, they sell first with a 45 to 60 day rent-back, so he gets his certainty that they’ll move only once, she keeps looking with real cash behind her offers, and the daughter gets a timeline she can plan around. Either way, the decision comes from the numbers and the couple’s energy level, not from whoever’s most anxious that week.
How I Help You Decide
When downsizing clients come to me, I start with three things: a realistic sale price and timeline for the current home, a look at the inventory in the places they’re considering, and a quick call with their lender or advisor to see what cash is available before the sale. From there the right order is usually obvious. I’ve helped older homeowners make this move since 2003, I hold the SRES® and CSA designations, and I’ve seen both paths work beautifully when they’re planned. If you’d like to map it out together, book a 30-minute call with me. If you’re moving to Santa Cruz County specifically, my post on selling and buying in Santa Cruz covers the local side.
Sources and Further Reading
- IRS Publication 523, Selling Your Home
- California State Board of Equalization: Proposition 19
- Fannie Mae Selling Guide B3-3.4-06: Employment-Related Assets as Qualifying Income
- California Civil Code Section 5550: HOA Reserve Studies
- California State Board of Equalization Publication 801: Base Year Value Transfers
- CFPB: Regulation B, Equal Credit Opportunity Act
Prop 19 Calculator
Can You Take Your Low Property Tax With You?
If you're 55 or older, Prop 19 may let you carry your current tax base to a new home anywhere in California. Plug in your numbers and see what your property taxes could look like after you move.
Estimate My Property Taxes →Frequently Asked Questions
Can I buy a new home before selling my current one?
Yes. Common approaches include a home equity line of credit opened before listing, a bridge loan, a securities-based line of credit, cash, or a buy-before-you-sell program.
Can I get a HELOC if my house is listed for sale?
Generally no. Most lenders won’t open a HELOC on a home that’s listed, so open it before you list.
Can retirees qualify for a mortgage?
Often yes. Lenders can count Social Security, pensions, and retirement and investment assets through asset-based underwriting.
What is a rent-back?
An agreement that lets the seller stay in the home for a period after closing, often up to 60 days, which can help if you must sell before buying.
Does buying first affect the Prop 19 base-year transfer?
If you buy first, the replacement generally must be worth no more than 100 percent of your original home’s sale value to carry over your assessed value in full.
Can I use my 401(k) or IRA to qualify for a mortgage when downsizing?
Often yes. Under Fannie Mae guidelines, lenders can divide your eligible retirement balance, after penalties and the funds you’re using for the purchase, by the loan term and count the result as monthly income.
Do I pay capital gains tax when I downsize?
You can exclude up to $250,000 of gain, or $500,000 if married filing jointly, if you’ve lived in the home two of the last five years. Gains above that are taxable, so talk with a CPA before you sell.
How long does downsizing take?
For most of my clients it takes four to nine months from the first lender meeting to closing on the sale. The cleanout and prep of a long-held home is usually what takes the most time.
Should I buy or sell first when downsizing in the Bay Area?
It depends on what matters more to you. Buying first is the easiest path: you move once and sell an empty, staged house, but you need a HELOC opened before listing, a bridge loan or cash, and you pay to carry two homes for a few months. Selling first is usually much cheaper because no bridge loan is needed and you know exactly what you netted, but it can mean moving twice unless you negotiate a 30 to 60 day rent-back.
How long can I rent back my house after I sell it?
Rent-backs of 29 days or less are usually handled with a Seller in Possession addendum, and 30 days or more with a Residential Lease After Sale. Buyers with standard owner-occupied mortgages generally have to move in within 60 days, so longer rent-backs are hard to negotiate unless the buyer is paying cash.
Are contingent offers accepted in Silicon Valley?
Sometimes, but they usually lose to non-contingent offers in competitive neighborhoods. They’re more realistic for senior communities, new construction and slower segments of the market.
What’s a bridge loan?
A bridge loan is a short-term loan secured by your current home that gives you cash to buy the next one, and it’s paid off when your current home sells. Rates and fees are higher than a standard mortgage and vary by lender, so compare quotes.
Free Downsizing Strategy Call
Before you start sorting decades of belongings or call a moving company... let's figure out where you're headed and how to get there.
Most downsizing regrets come from doing things in the wrong order. In 30 minutes, we’ll talk through what your home may be worth, whether to buy or sell first, how Prop 19 could affect your property taxes, what the house actually needs before listing, and a realistic timeline for your move—so the process feels manageable, not overwhelming.
Book My Downsizing Strategy Call →Senior Friendly Homes in Silicon Valley South
2
3
4
5
6
7
8
9
10
11
12
13
14
15
16
17
18
19
20
21
22
23
24
25